We know what’s coming and we are prepared.

🇺🇦⚔️🇷🇺 The Black Sea war sends world wheat prices up
The US Department of Agriculture has cut its forecasts for Russian and Ukrainian grain exports because of the Black Sea shipping war, and every rival exporter's price has gone up.
The department's monthly Grain: World Markets and Trade report, published on August 12 by its Foreign Agricultural Service, cuts Russia's 2026/27 wheat exports to 46mn tonnes and Ukraine's to 13.5mn, blaming disruption to Black Sea shipping since hostilities intensified in mid-July.
The report's own headline is elsewhere - EU grain imports rising and exports falling on the back of a crop wrecked by heat and drought - but the two findings are the same story from opposite ends.
Grain trade has spent four years being reshaped by this war, and this is the month the price data caught up with the shipping data. Russia has been the world's cheapest large wheat seller throughout; in August it is discounting while everyone else raises quotes, because a discount is worth nothing if the cargo cannot leave Novorossiysk. All three of that port's big grain terminals stopped work this week.
Since the July estimates, wheat export quotes rose sharply among every major exporter apart from Russia. Russian quotes fell $3 a tonne to $224 on early harvest pressure and mounting supplies with some export routes inaccessible.
EU quotes jumped $25 to $262 a tonne on expected import demand despite a much smaller crop; US quotes rose $26 to $321, Canadian $20 to $292, Australian $13 to $291 and Argentine $12 to $239 - still the next most competitive after Russia. The US season-average farm price was raised 20 cents to $6.20 a bushel.
A seller with the world's cheapest wheat and no way to load it is not a price-setter. Russia is discounting into a market that is repricing upward around it, which is the clearest measure yet of what the port campaign has cost Moscow.
The department cut Russian wheat exports for 2026/27 by 1.5mn tonnes to 46mn, citing "disruptions in the Black Sea hindering shipments, especially from ports in the Sea of Azov", and Ukraine's by 1mn tonnes to 13.5mn, on disruption to its deep seaports. Kazakhstan and Canada picked up 1mn tonnes each, to 10mn and 28.5mn.
EU wheat and coarse grain production for 2026/27 is now forecast at 264.8mn tonnes, down 8% on the year, after excessive heat and dryness through the late spring and summer cut yields on wheat and barley. Corn is forecast at 50.2mn tonnes - which would be the smallest EU corn crop in nearly 20 years.
EU corn imports are raised 1mn tonnes to 23.5mn as a result, and its own corn exports cut to 1.6mn. Barley exports, at 9.1mn tonnes in 2025/26 and the highest since 2015/16, are forecast to fall 19%.
Filling that gap is harder than it looks. Ukraine, normally a top corn supplier to the EU, is dealing with the same Black Sea shipping disruption; Brazil's exports have started slowly despite a record crop, as domestic biofuel demand absorbs the corn; and Ukrainian wheat into the bloc is still constrained by EU import policy, particularly for the Visegrad Group. The department notes significant recent EU purchases of US corn instead.
🔗 https://www.intellinews.com/the-black-sea-war-sends-world-wheat-prices-up-461199/
The U.S. Election Assistance Commission’s official 2024 report shows that Texas processed 2,900,357 new valid voter registrations between the 2022 and 2024 elections, representing 56.5% of 5,133,464 voter-registration transactions.
Another 2,165,514 transactions (42.2%) involved updates to existing registrations.
During that period, Texas required applicants to affirm U.S. citizenship under penalty of law but did not routinely require a birth certificate, passport or naturalization papers with registration applications. The 56.5% share exceeded the national average of 25.3%, although other states reported even higher percentages. In September 2026, Texas officials referred 117 potential noncitizen-voting cases for investigation.
Official Election Administration and Voting Comprehensive Report buried this information all the way on page 193 of the document.
55% "new" Texas voter registrations might explain how leftists won in the midterms there.
🇺🇸 The Real Architect of the Iran Mess and its not Pete Hegseth
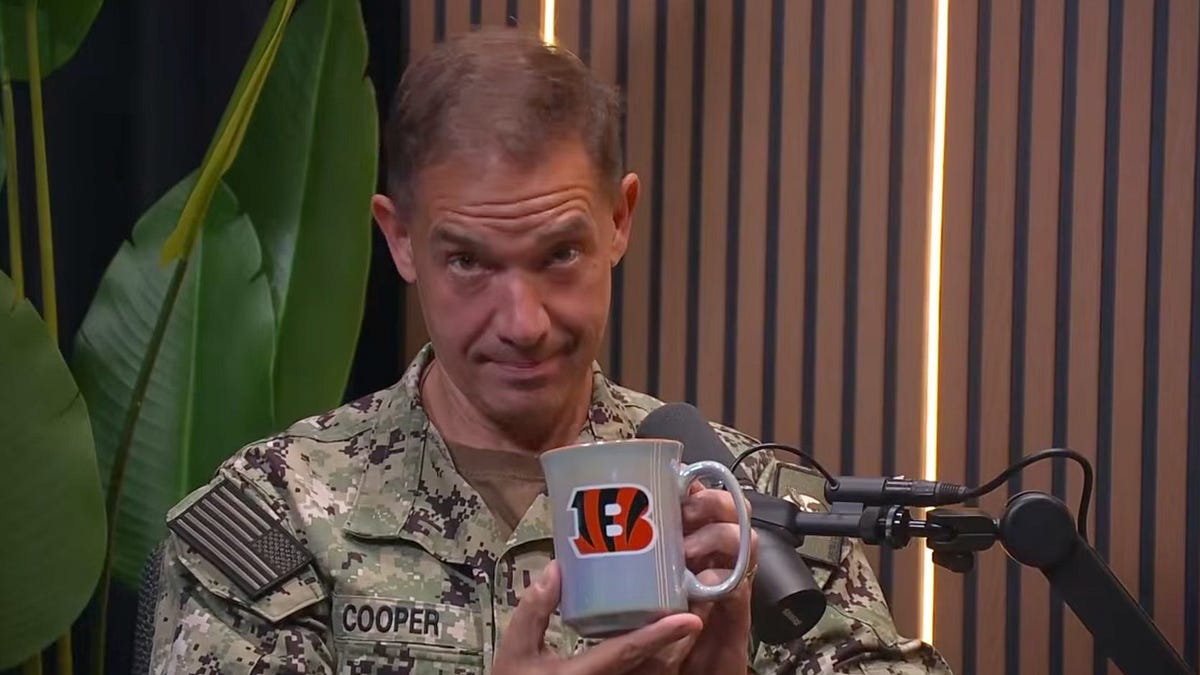
Yesterday, the military command for the Middle East unveiled its new podcast, “Inside CENTCOM,” featuring its commander, Navy Admiral Brad Cooper — the man most responsible for the Strait of Hormuz crisis and skyrocketing gas prices.
The timing couldn’t be more hilarious. The entire country just voted against his Iran war, and there’s Cooper, the architect, grinning and chatting up his workout routine, love of french fries and basketball. Asked about Operation Epic Fury, he says only that “I just couldn’t be prouder” and how even amidst the war he guards the “sanctity” of his workouts.
Considering that Cooper never bothered to make keeping the Strait of Hormuz open an objective of the war — which sent oil prices soaring — maybe he should’ve spent less time working out. But judging from his breezy podcast appearance, Cooper sleeps like a baby.
“Let me be clear: the Strait of Hormuz is controlled by the...
Things I am not afraid of (and you shouldn't be, either):
1. Trump escalates the Iran War. The U.S. will not win, Iran will prevail, U.S. will be expelled from Middle East and Israel will be destroyed.
2. Trump passes amnesty with Democrats. This was always in the cards for Trump's final 2 years, with or without a Democrat majority. There was never going to be mass deportations under ZOG. They aren't leaving without major economic collapse, civil unrest or race war.
3. Woke censorship comes back. All it did was piss off and radicalize White people the first time. The "vibe shift" did nothing except allow rightoids to cheer ZOG on Twitter.
4. Whites become a minority in America. This will the beginning of a genuine White nationalism and eventual breakup of the republic. It's also inevitable at this point. Nationalism only grows under occupation and adversity.
5. Democrats fail to end the Iran war. This will cause huge unrest within the Democratic grassroots & open revolt ...